Garcia Real Estate Group April 14, 2022
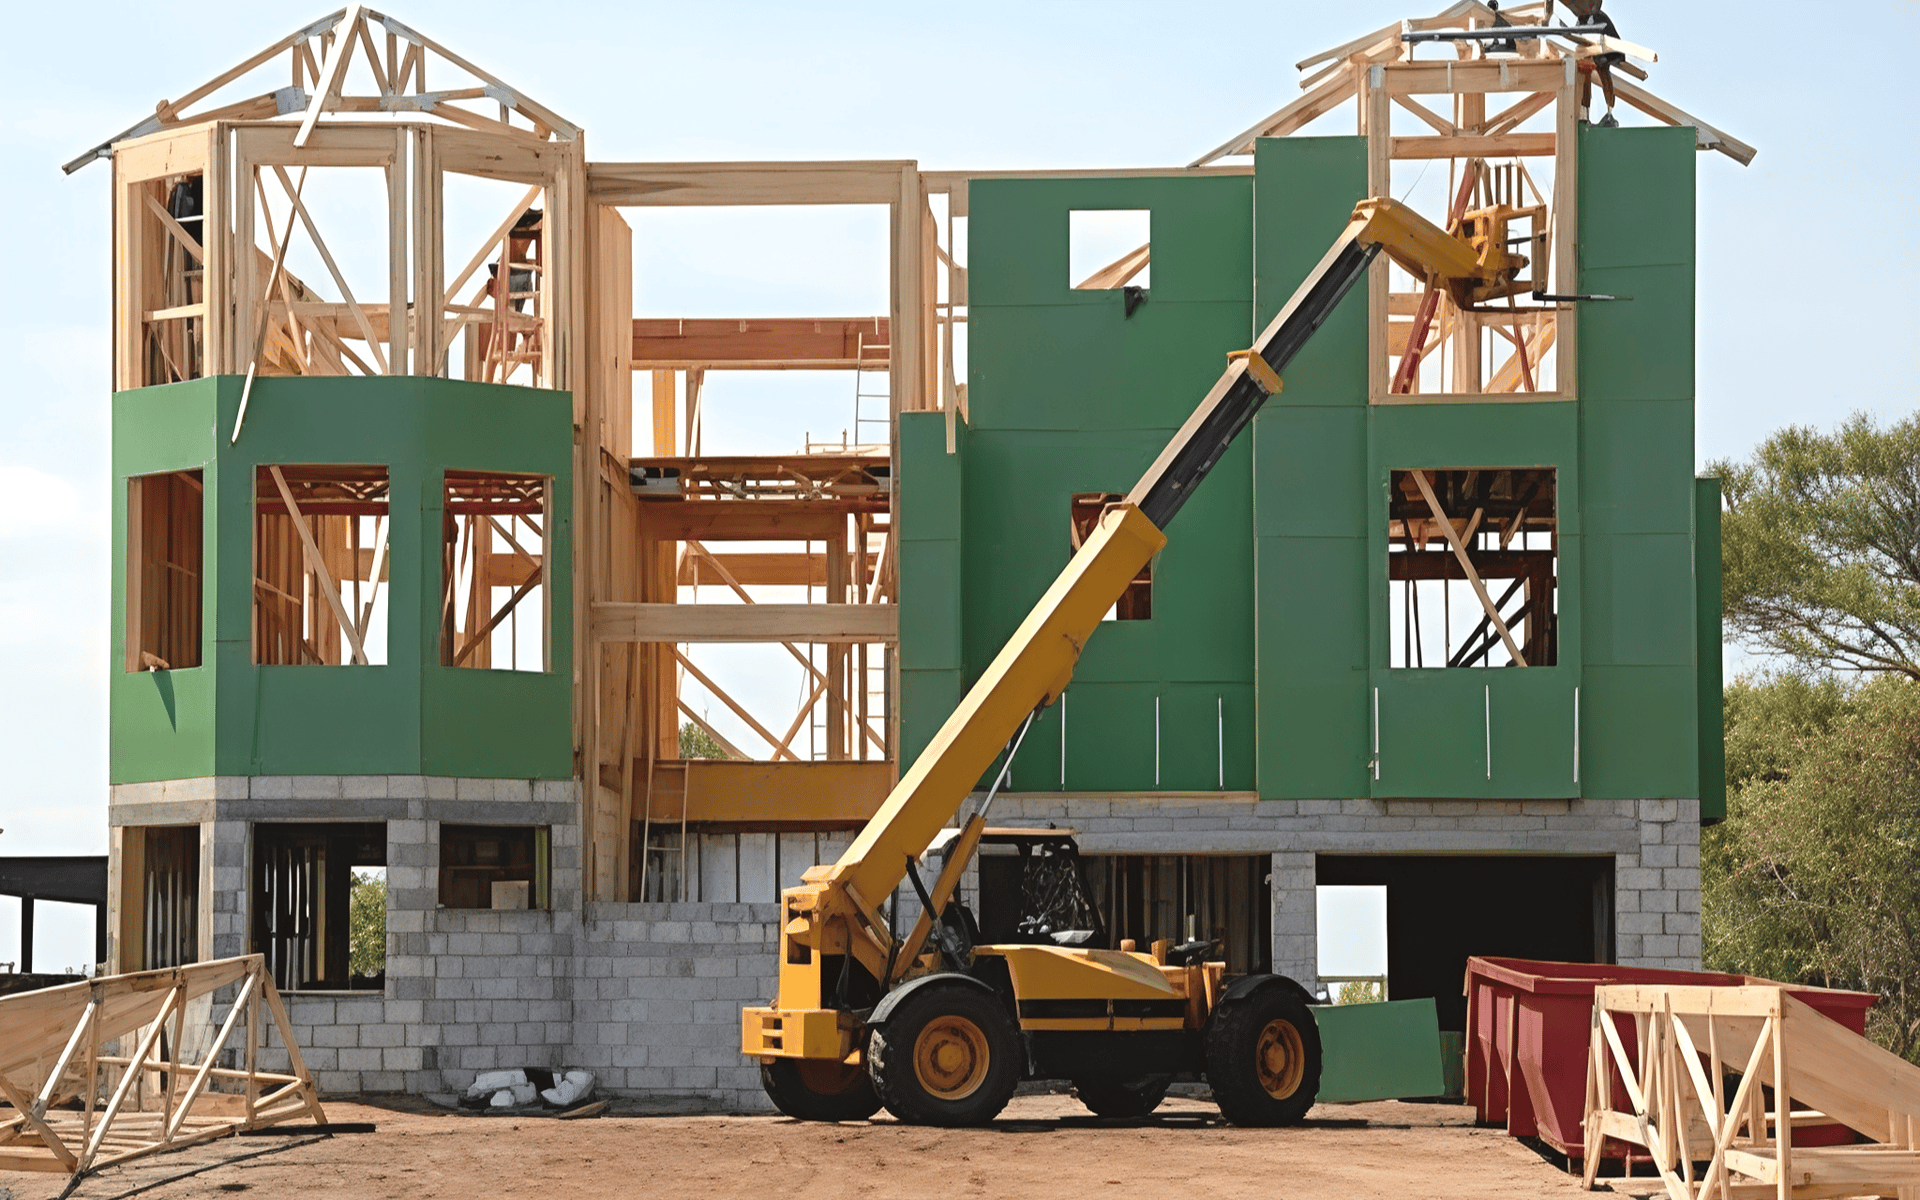
As of late, Aspiring homebuyers in Texas are faced with the following options: buy an existing house at an increased market rate, wait for prices to go down, or build a new house from scratch. If you’re in the last category, you’re probably wondering: “How much does it cost to build a house anyway?” and “Can I afford it?” This is where construction loans come in.
A home construction loan or “self-build loan” is a short-term loan that’s used to finance the construction of a new home, renovation or restoration project. Due to the extra risk involved, construction loans typically have higher interest rates than traditional mortgage loans.
In most cases, the homebuyer will take out a construction loan to fund costs over the duration of the project. Construction loans typically cover the following costs: land, labor, architectural designs, contingency reserves, building materials and permits. Construction loans are good for a year or so, which is the average period of time it takes to build a custom home from start to finish.
Once a construction timeline is set with the builder, the borrower is given a “draw schedule” which details when the builder will receive payments over the course of the building process. Unlike mortgage loans, construction financing is distributed in stages instead of one lump sum. After the home is built, the borrower may be able to refinance the construction loan into a permanent mortgage (this is called a “construction-to-permanent loan”) or take out an “end loan” to pay off the balance. However, just keep in mind that the repayment terms of your construction loan will depend on your finances and the lender.
The answer to this question brings us back to the issue of extra risk. When a lender issues a mortgage loan, the home itself is collateral in the unfortunate event that the borrower defaults on their mortgage payments. With construction loans for new builds, the lender is taking a bigger gamble (as there is no existing home to claim as collateral if things go awry). To minimize risk, lenders may require a minimum credit score of 680 along with other requirements like a low debt-to-income ratio and a specific income range.
Curious to know more about construction loan rates and whether or not this is the way to go for your real estate needs? Let us connect you with one of our preferred lenders to discuss your options.
Discover more market perspectives, neighborhood knowledge, relocation insights, and real estate guidance from Haley Garcia Group.
Fall is one of the more strategic times to buy in The Woodlands and the greater Houston area.
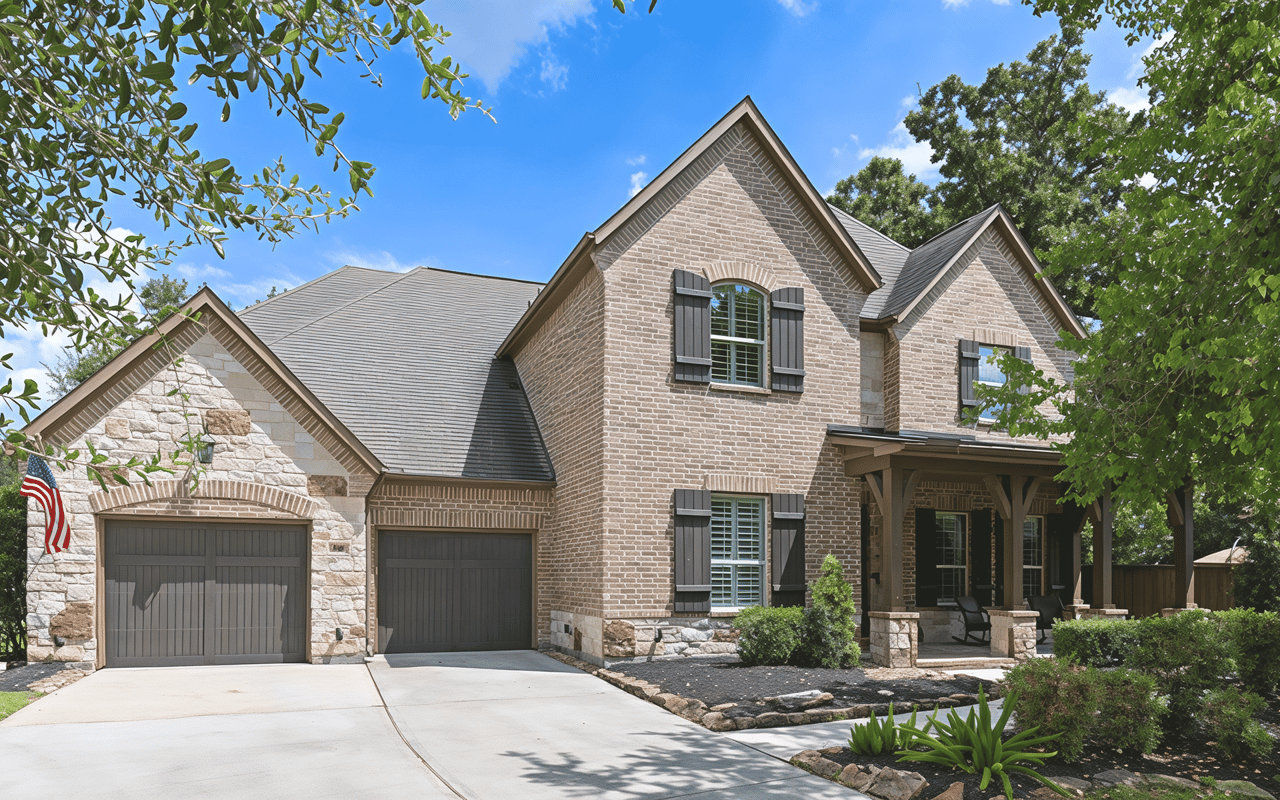
It pairs refined interiors and a light-filled main living area with a media room, a game room, and a backyard.
It is one of the questions Garcia Real Estate Group hears most, and it rarely has a simple answer.
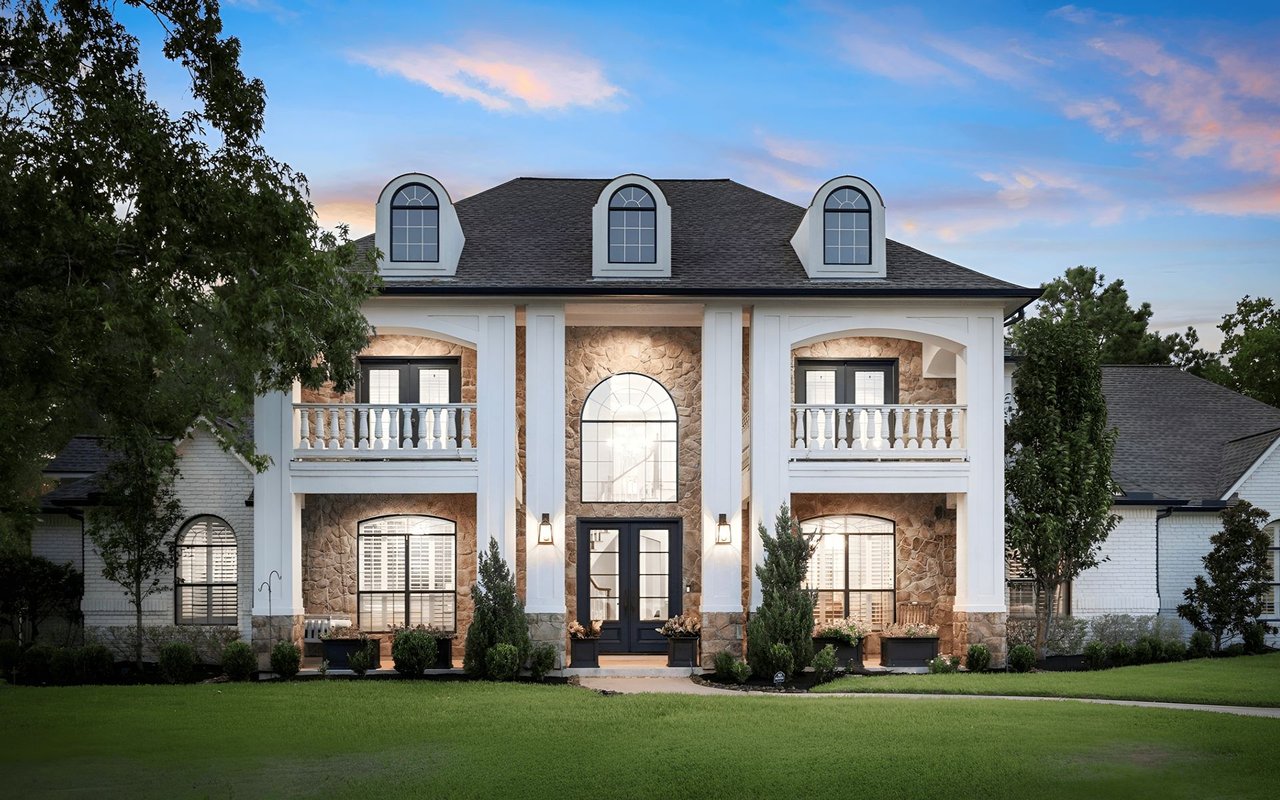
A home built for sophisticated family living, on a lot with room to breathe, in a location that keeps the best.
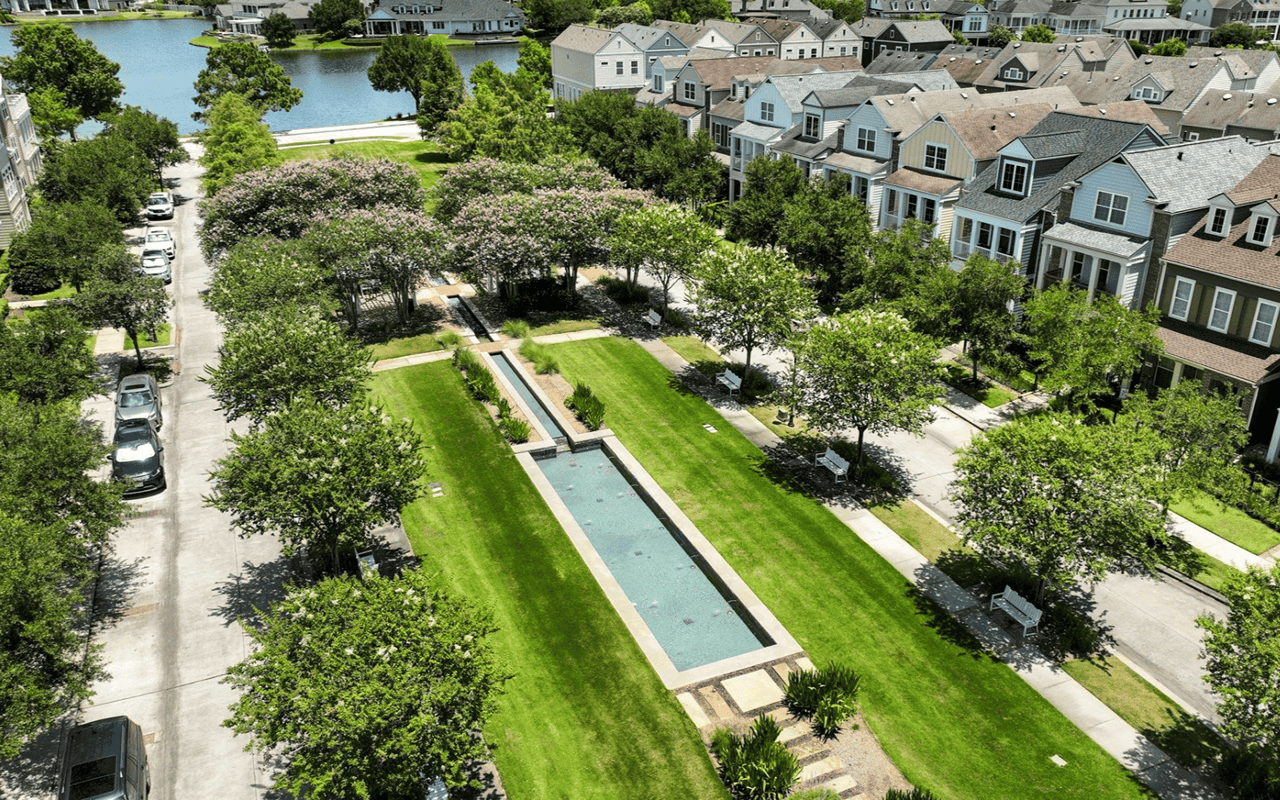
For anyone considering a move to the Houston area, it’s worth seeing in person before deciding.
Inventory is up, homes are taking longer to sell, and pricing has leveled off across most segments.
Work with a team that combines 25 years of experience, local expertise, and personalized service to help you find your place in the world.